
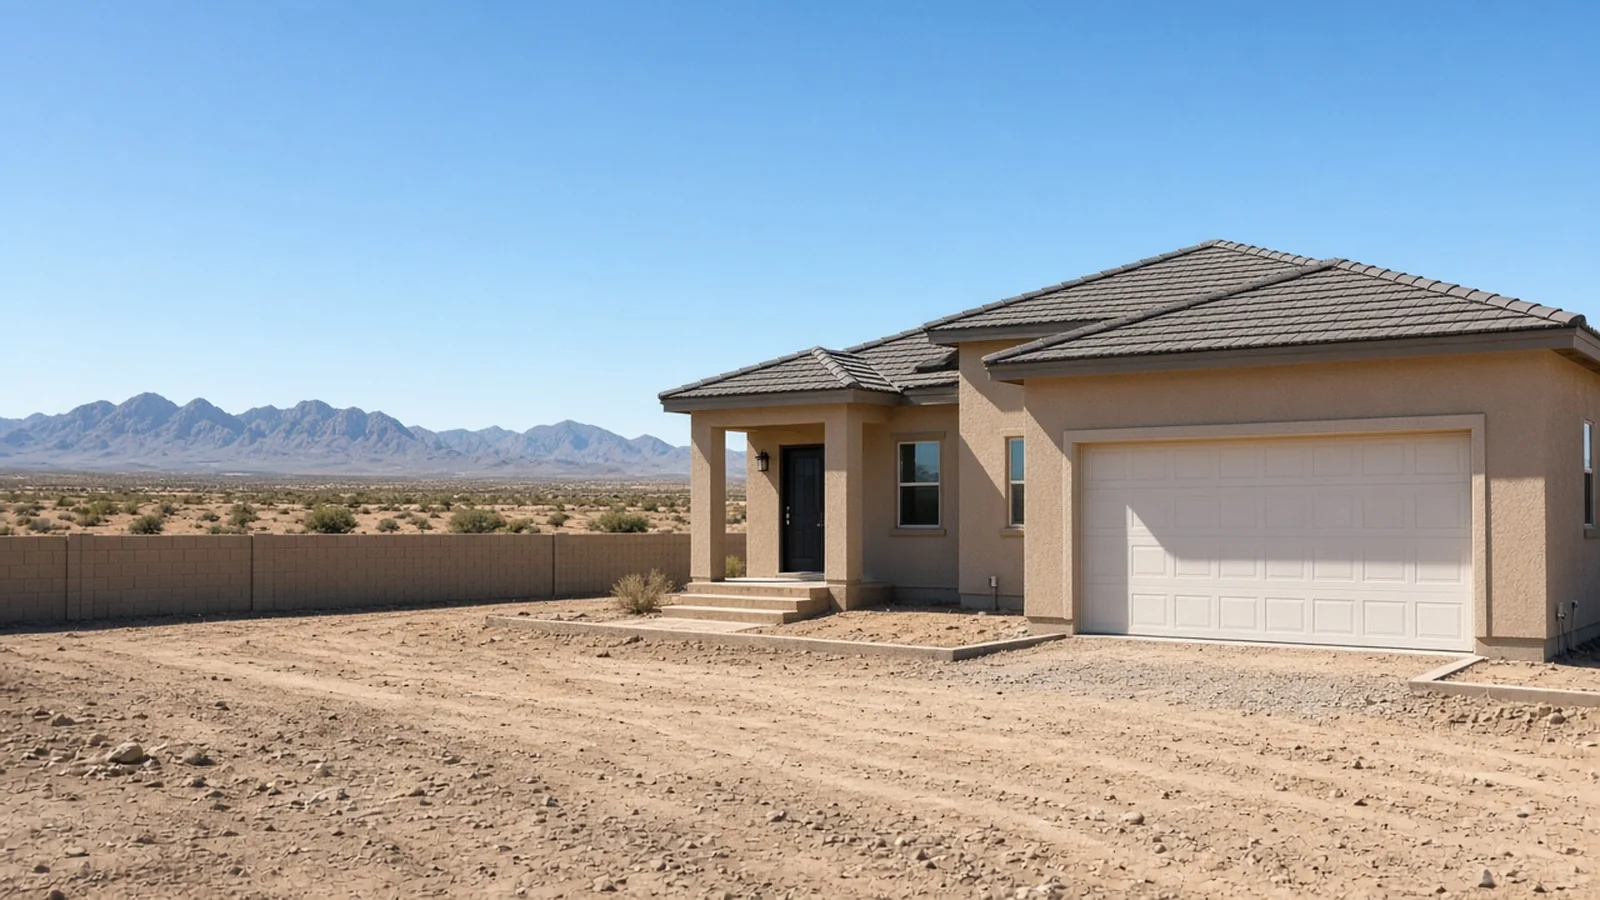
Buckeye · Far West Valley
A Buckeye, AZ mortgage broker for homes still being built
In Buckeye, the house you're buying may not be finished yet. I'm Paige Martinez (NMLS #214634), a Phoenix mortgage broker and loan originator licensed across Arizona. I plan your loan and your rate lock around the builder's real timeline, so a delay doesn't cost you the house or the rate.
Your Buckeye home may still be a frame. That's normal.
Buckeye is one of the busiest places in the Valley for new homes. New phases keep opening in master-planned communities, from Verrado to developments farther out, and many buyers sign a contract before the walls go up.
That's exciting. It also means your loan runs on two calendars, the builder's and the lender's, and they don't always agree. My job is to make them work together.
Tell me how finished the home is today. That one answer shapes everything else.
Buy a home · New construction
I don't have a Buckeye office. I work from Shea Blvd in Phoenix, and Buckeye clients start with a phone or video call. Appraisers, inspectors, and title are local to the far West Valley.
Estimate your payment on the calculator with HOA included. It's an estimate, not a quote. Then plan a realistic timeline, because a home still under construction won't close in two weeks.
Down payment help: Phoenix Open Doors only covers homes inside Phoenix city limits, so it doesn't apply in Buckeye. Home in Five Advantage (Maricopa County) and HOME Plus (statewide) can. These programs add steps, like a homebuyer class, so the builder's timeline has to allow for them. Some addresses on Buckeye's outer edges may also show up on the USDA eligibility map. The map decides, so we check your exact address together. down payment assistance USDA loans
How finished does the home need to be?
To close a standard purchase loan, the home has to be complete enough for an appraiser to value it and for the city to sign off on it. A home that looks done on Saturday can still be waiting on a final inspection on Monday.
Here's how I think about it:
- Finished or nearly finished ("spec") homes. These can usually close on a normal purchase schedule once the final inspection is done.
- To-be-built homes. These can work well, with more planning. I'll need the builder's estimated completion date in writing, and we both plan for it to move.
- Homes that are still early. If the home is too early in the build for a purchase loan, I'll tell you up front. A construction loan is a different product, and I'll be clear about what I can and can't do.
Missing appliances, unfinished landscaping, or a builder's to-do list that isn't done can each add a lender requirement before closing. I flag these early so they don't land on closing week.
Rate locks and builder dates, planned together
A rate lock holds your interest rate for a set number of days. Builders deal with weather, labor, and supply delays. Those two calendars don't line up on their own, so I build in cushion from the start.
- Name your hard date. If you need to move before a school year starts or a lease ends, tell me in the first call. I'll tell you whether a home still under construction fits that date, or whether a finished resale nearby is the safer path.
- Compare the builder's offer in writing. If the builder offers an incentive tied to their lender, get it and their Loan Estimate (the standard form showing rate, fees, and cash to close) in writing. I'll compare it side by side with a loan I shop using the same down payment. You choose.
- Keep upgrades inside your pre-approval. Every option adds to the price and the loan amount. Before the design center, let's confirm your numbers.
- Know your earnest money. Deposits on new construction are often larger and less refundable than on a resale. Read the builder contract with your agent. I'll tell you what the loan side needs.
New construction
A longer timeline, and how to stay ready for it
The wait between contract and closing runs longer on new construction, and that gives your loan more time to change. Protect it while you wait:
- Keep your credit steady. Don't open new cards or finance furniture before closing.
- Keep your paperwork moving. When I ask for an updated pay stub or bank statement, send it the same day. Distance isn't the delay. Missing documents are.
- Get your insurance quote early. The payment isn't complete until it's in.
- Plan for taxes. The tax on a new-build listing often reflects only the lot. I'll estimate your real taxes before you sign.
Text me before you change jobs, move money between accounts, or make a big purchase. Those are the things that change a loan late in the game.
Comparing Buckeye with nearby cities?
- Goodyear: West Valley living with more finished homes on the market. Goodyear
- Surprise: planned communities to the north. Surprise
- Avondale: a resale mix closer to Phoenix. Avondale
Your next step: Call or text (602) 448-4470 with the community, the builder, and the estimated completion date. Have the builder's options sheet handy. When you're ready, start your secure application. apply
Buckeye mortgage questions
Can I get a mortgage on a Buckeye home that isn't finished yet?
Should I lock my rate when the builder says 60 days?
Can I use Phoenix Open Doors in Buckeye?
Do you have a Buckeye office?
Ready when you are.
Buying, refinancing, or holding a quote you want checked? Tell me your goal and I'll map out your next step. Not ready to talk? Grab the Pre-Approval Checklist and start there.