
Buying · October 6, 2026
New construction in Gilbert, Mesa, or Queen Creek
The monthly number on the model-home whiteboard isn't a Loan Estimate. Builder credits, your close date, and taxes on the finished home belong on one worksheet. Here's how to line them up before you sign with a builder.
- A spec home and a to-be-built home are different loans. A spec home is already built or nearly done. A to-be-built home has a completion date that can move.
- Builder credits only help if they hold up. Compare them against the same loan from a lender you choose.
- Your first-year taxes may be low. Early tax bills can reflect the lot, not the finished house. Plan for the full amount.
- Long builds need a lock plan. Ask about lock length and extension costs up front.
Who it fits
You're buying a new home to live in, in Gilbert, Mesa, Queen Creek, or nearby, and a builder is asking you to pick a close date. For the whole metro: new construction mortgages
How it works
Send me the builder contract, the incentive sheet, and how you're paid before anyone treats a sales-office number as your loan. Tell me how far along the house is.
What it costs
Closing cost credits, rate buydowns (paying upfront for a lower rate), and design-center allowances all show up as credits and costs. A low payment that hides a buydown still has a cost.
Spec, to-be-built, and move-in ready
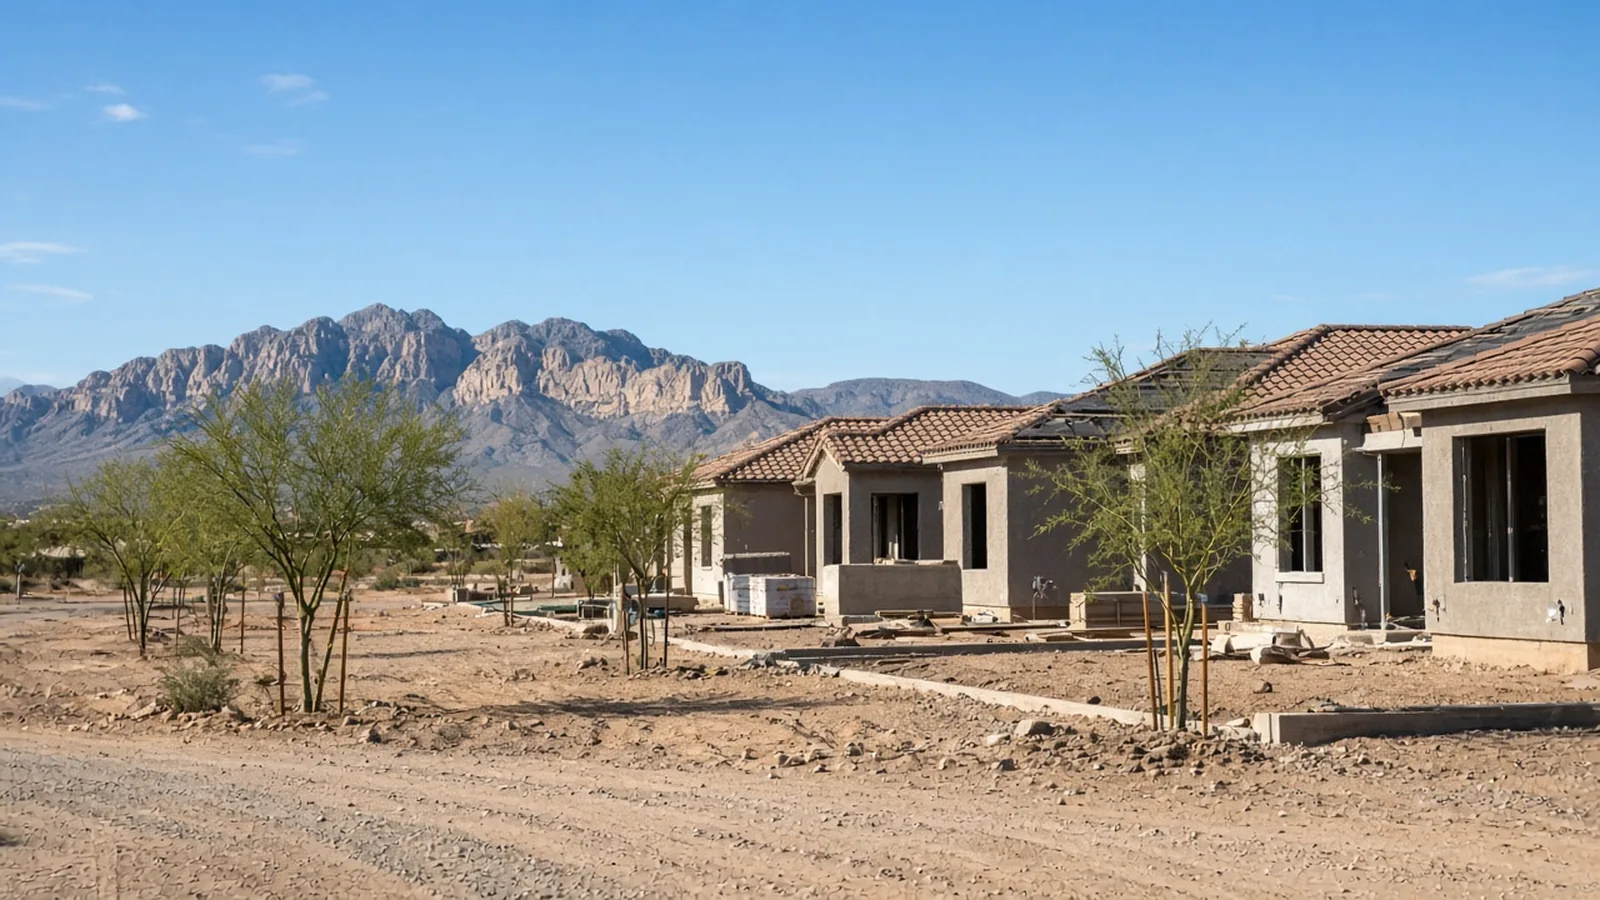
A finished spec home in Gilbert can work much like buying a resale home, with a few tax wrinkles. A to-be-built home in Queen Creek or Mesa has a completion date, design options, and often a builder who wants their preferred lender in the paperwork. A rendering isn't an appraisal, and a dirt lot isn't a close date.
If the builder wants you to use their lender, read the contract. The incentive may depend on it, but you may still be free to compare. As a broker, I'll tell you whether a loan I can shop fits this builder and your dates, or whether the builder's lender is the cleaner path.
I'm Paige Martinez, a mortgage broker at Home Loans by Paige, 3420 E. Shea Blvd, Suite 200, Phoenix. This is education, not a rate quote or a commitment to lend.
Purchase steps: buy a home City pages: Gilbert · Mesa · Queen Creek
Put builder credits side by side
Send me the incentive sheet with the lot number. I'll line it up against the same loan amount and down payment so you can see what holds up. A big credit on page one can be offset by fees on page two.
Upgrades change the price, and sometimes the appraisal. An upgraded HVAC system, an extra garage bay, or a pool isn't free because you picked it in the design center. If the credit only works with the builder's lender, I'll show you whether it beats the difference in rate and fees.
Taxes on a house that isn't finished yet
New homes in Mesa, Gilbert, and Queen Creek often show a low first-year tax bill because the county hasn't valued the finished house yet. Arizona caps how much a home's taxable value can rise each year, but the cap doesn't apply when improvements are added, like a new house on what used to be a lot. That's why the escrow part of your payment (taxes and insurance collected monthly) can jump in year two.
A builder quote based on the lot tax isn't your payment once the house is done. I separate principal and interest from taxes and insurance so you see each piece. Get a real insurance quote while you're still touring models, not the week before closing.
A long build needs a lock plan
A rate lock holds your interest rate for a set time. A six-month build needs a lock that can last through delays, or a plan to float (wait to lock) that you understand. Ask how extensions work and what they cost. If the slab pours late, the loan closes late, so I plan a realistic close date.
Selling a home to pay for the build? Your equity isn't cash until that sale closes. Bring your payoff and whether your home is listed. A lease-back (renting your old home from its buyer for a short time) changes move dates and insurance, so put it on the worksheet. If keeping your current home makes more sense, I'll tell you. refinance
What to bring
- Builder, community, and lot number or address
- How far along the house is: dirt, framing, or finished
- The incentive and options sheet
- How you're paid, and the down payment in your accounts
- Whether you're selling another home this season
If two lots share a price, send both. The goal is the house you can close on, not the model that won the weekend tour. Call or text (602) 448-4470.
Questions from the model home
Can I use a regular purchase loan if the house isn't finished?
Should I use the builder's preferred lender?
Will my payment stay the same after the first year?
Is this only for Gilbert?
Who helps with new construction loans in the East Valley?
Ready when you are.
Buying, refinancing, or holding a quote you want checked? Tell me your goal and I'll map out your next step. Not ready to talk? Grab the Pre-Approval Checklist and start there.